
Here are the key takeaways from Thursday’s CSO release on Irish tourism, which delivered mixed news for the sector:
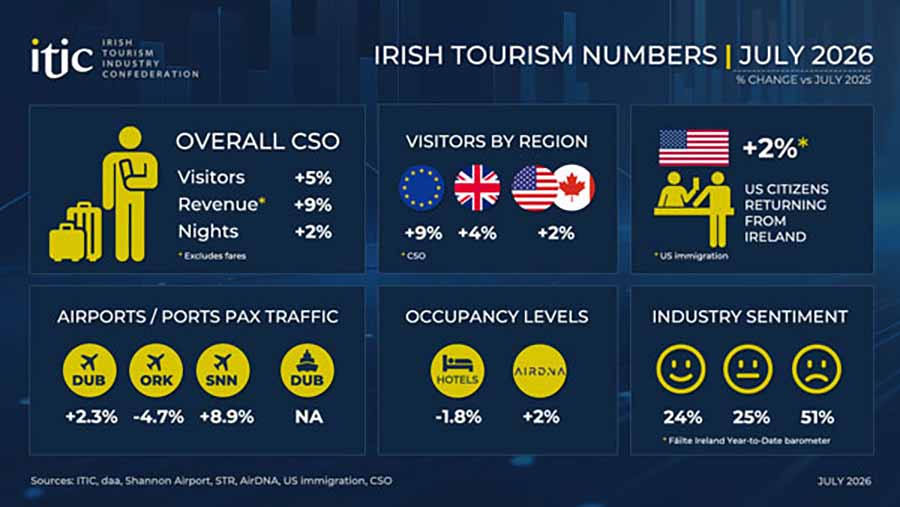
- Visitor numbers rose: 676,300 foreign overnight visitors completed trips to Ireland in July 2026, up 5pc on July 2025 and up 3pc on July 2024.
- Year-to-date numbers recovered strongly: January–July 2026 totalled about 3.9 million overseas visitors, up 13pc on the same period in 2025 and fractionally ahead (+0.4pc) of 2024.
- Spend improved in the month but overall tourism revenue has still not surpassed 2024 levels: July expenditure (excluding fares) was €681 million, up 9pc on July 2025 (€624m) and up 5pc on July 2024 (€650m). However, year-to-date spending (including fares) remains below the equivalent 2024 period (reports note it is still nearly 2pc lower), and industry commentary highlights that revenue has not yet moved beyond 2024 levels.
- Most markets remain well behind pre-pandemic levels: Overall inbound numbers in July were down around 41.5pc on pre-pandemic; Britain roughly –41.5pc, North America –30.9pc, and Continental Europe –48pc.
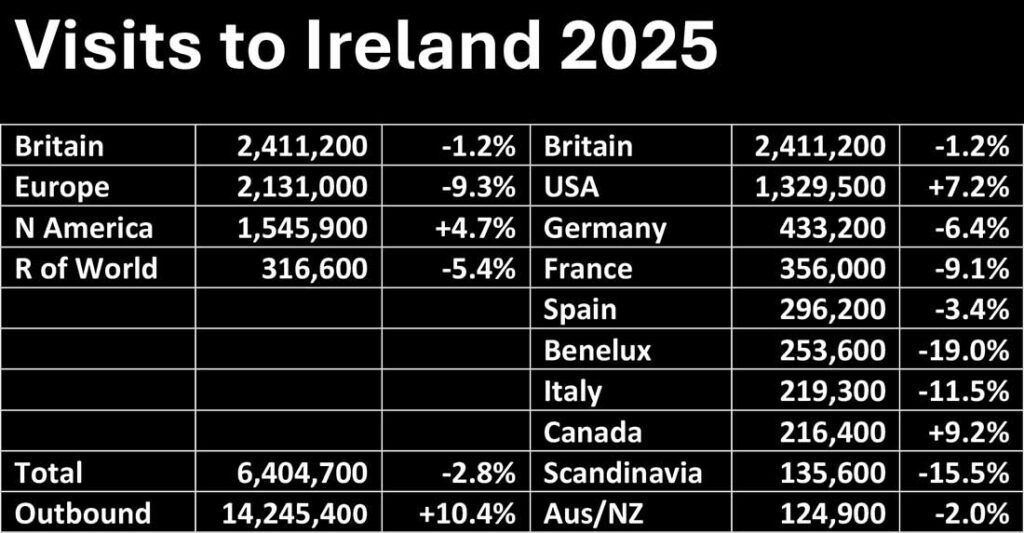
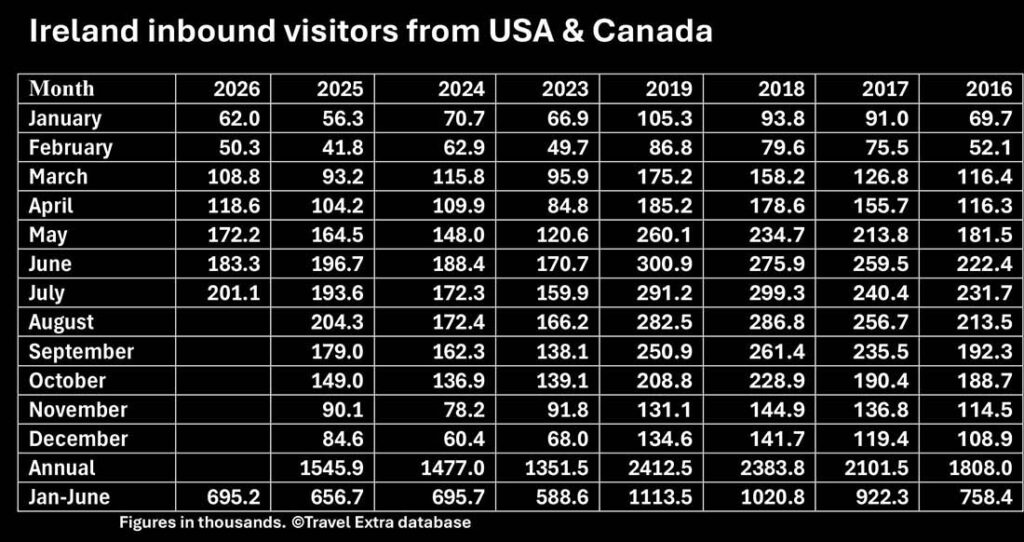
- USA/North America recovery from the June dip is important: North American visitors rose about 2pc in July (to ~201,100), recovering from a ~7pc drop in June. They accounted for 30pc of visitors but a much higher 44pc of spend (€300 million), confirming their status as the highest-spending market. Year-to-date US visits reached ~775,400 (+7.6pc).
- Big drop in numbers from France: French visitors fell sharply to 28,400 in July, down 23pc on July 2025 and still ~48.5pc below pre-pandemic levels.
- Average length of stay shortened: It fell to 7.6 nights in July 2026 from 7.9 nights in July 2025 (a ~3pc decline). Total nights rose only 2pc (to 5.2 million) despite the stronger visitor growth.
- Market shares were evenly split at the top: Britain and Continental Europe each held 32pc of visitors, North America 30pc, and Rest of the World 6pc. Growth was driven by Continental Europe (+9pc), Britain (+4pc), and North America (+2pc); Rest of the World edged down 1pc.
- Holiday travel dominated: 50pc of overnight foreign visitors came primarily for Holidays/Leisure & Recreation, 29pc for Visiting Friends & Relatives, and 11pc for Business.
- North American visitors remain disproportionately valuable: Despite making up only 30pc of volume, they generated 44pc of the €681 million spend, far outpacing Continental Europe (31pc/€209m) and Britain (19pc/€127m). Mean spend per visitor also rose.
These figures show volume recovery (especially versus the weaker 2025) alongside ongoing challenges around shorter stays, lagging pre-pandemic volumes in most markets, and revenue that has not yet fully regained 2024 peaks.
Market by Market
- Ireland outbound numbers were 1,475,000 in July, down 0.6pc on July 2025 and up 52.2pc on pre-pandemic. Rolling annual was 14,232,000, up 6pc on the twelve months to July 2025.
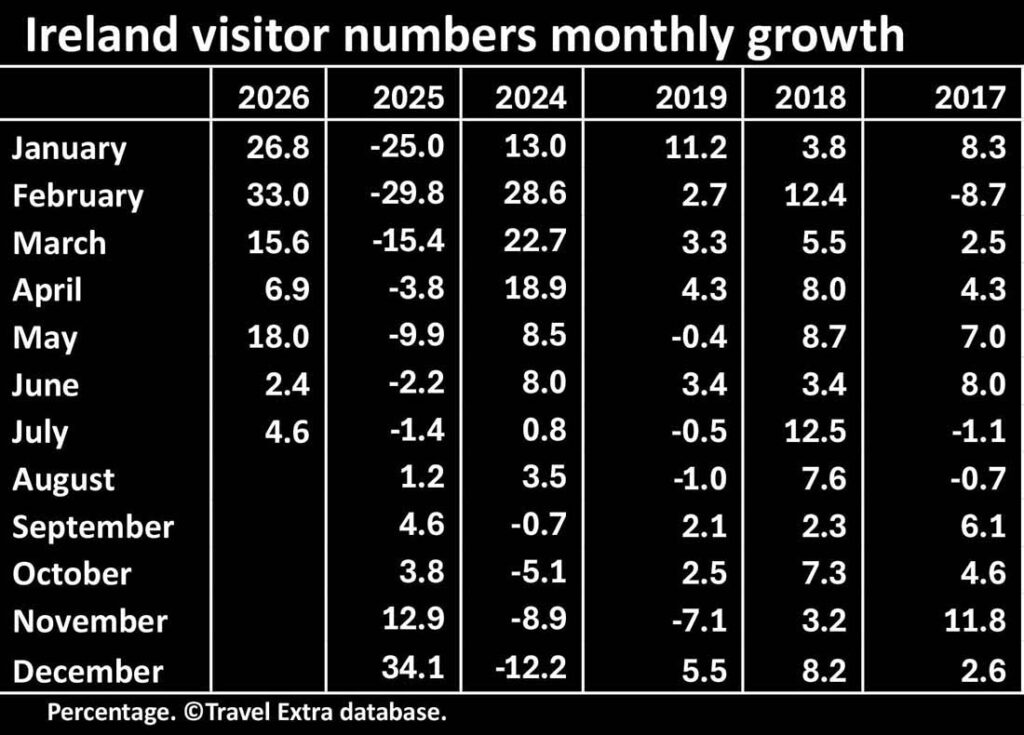
- Ireland inbound visitor numbers in July were 676,300, up 4.6pc on July 2025 and down 41.5pc on pre-pandemic. Rolling annual was 6,847,000, up 9.3pc on the twelve months to July 2025.
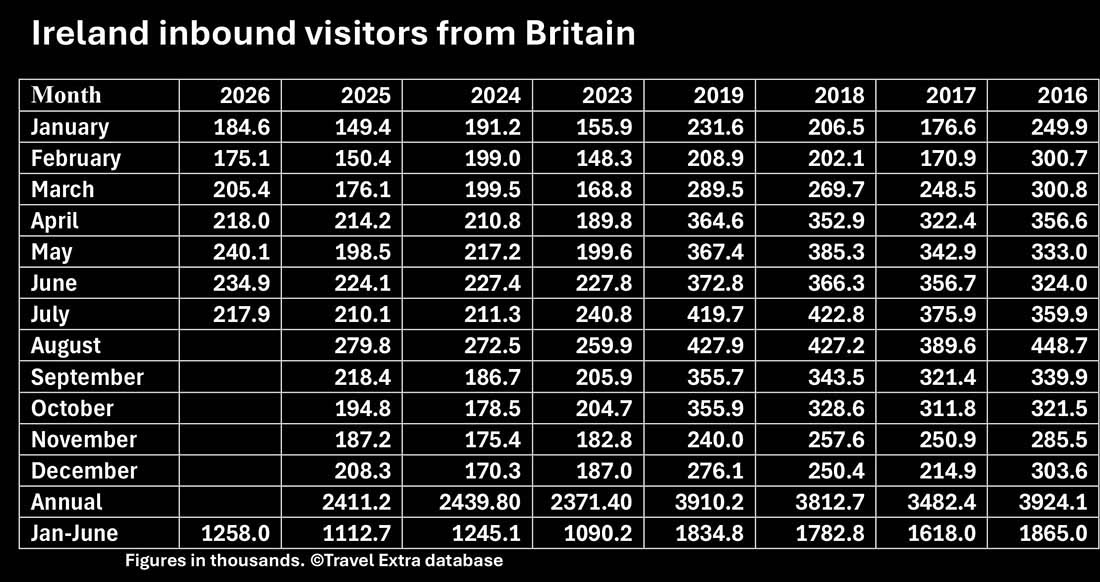
- Ireland inbound visitor numbers from Britain in July were 217,900, up 4.6pc on July 2025 and down 41.5pc on pre-pandemic. Rolling annual was 3,564,000, up 3.7pc on the twelve months to July 2025.
- Ireland inbound visitor numbers from North America were 201,100 in July, up 2.3pc on July 2025 and down 30.9pc on pre-pandemic. Rolling annual was 1,603,300, up 10.1pc on the twelve months to July 2025.
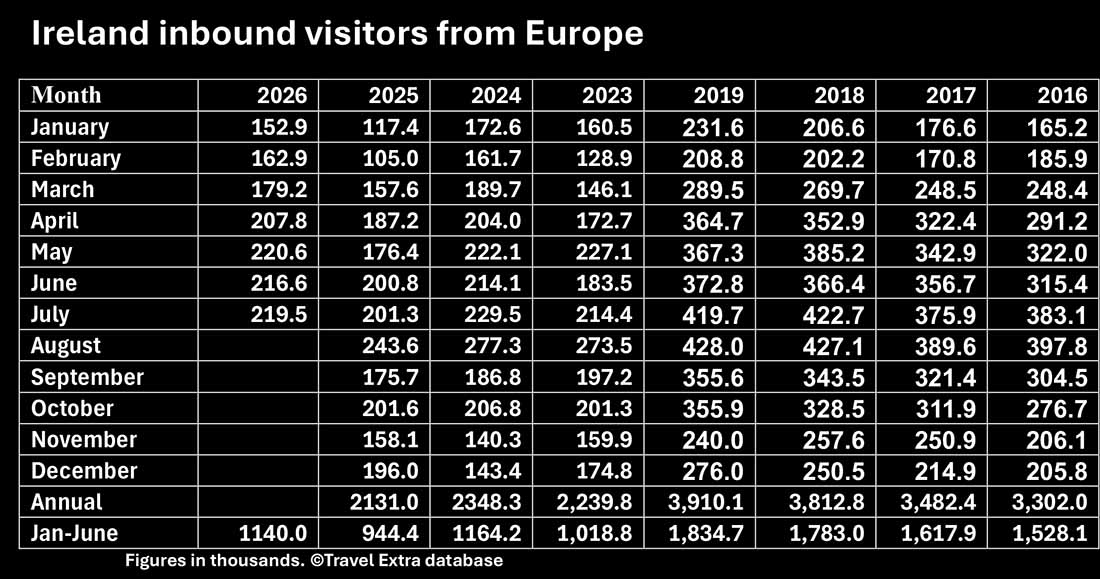
- Ireland inbound visitor numbers from Europe were 219,500 in July, up 9pc on July 2025 and down 48pc on pre-pandemic. Rolling annual was 2,334,500, up 8.5pc on the twelve months to July 2025.
External link to CSO release


Destination guides to Ireland’s counties
Antrim – Armagh – Carlow – Cavan – Clare – Cork – Derry – Donegal – Down – Dublin – Fermanagh – Galway – Kerry – Kildare – Kilkenny – Laois – Leitrim – Limerick – Longford – Louth – Mayo – Meath – Monaghan – Offaly – Roscommon – Sligo – Tipperary – Tyrone – Waterford – Westmeath – Wexford – Wicklow
CSO inbound tourism stats for Ireland
Overall – Australia/NZ – Benelux – Britain – Canada – Europe – France – Germany – Italy – North Anerica – Scandinavia – Spain/Portugal – USA – Outbound –